Home / Real-World Applications
Monte Carlo Simulation Basics: Using Random Sampling to Solve Hard Problems
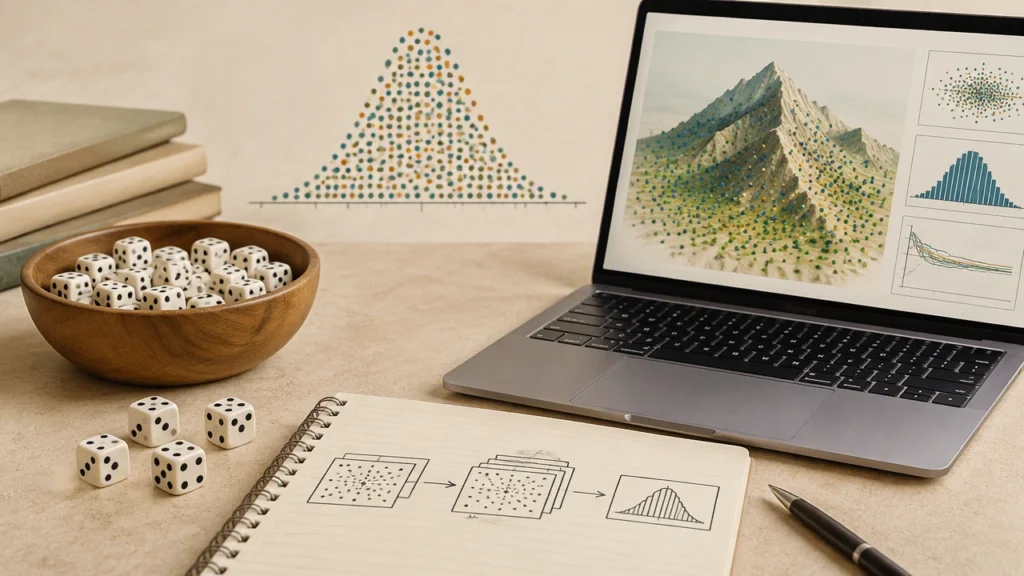
Many problems in science, engineering, and data analysis involve uncertainty, high-dimensional spaces, or integrals that are difficult to solve with closed-form formulas. In probability and the mathematics of chance, one powerful idea is to use random sampling as a computational tool. Instead of trying to calculate an exact answer directly, a computer can draw many random scenarios, combine the results, and converge on a useful estimate. This is the core idea behind Monte Carlo methods.
What a Monte Carlo simulation is and how it works
A Monte Carlo simulation is a technique that estimates a quantity by repeatedly sampling from a probability distribution or a process model. The computer generates many random inputs, runs the model for each input, and then aggregates the outputs. As the number of samples increases, the estimate usually becomes more stable and accurate, governed by well-understood statistical behavior.
Conceptually, the workflow is straightforward:
- Define a model that maps inputs to outputs.
- Specify probability distributions for uncertain inputs.
- Draw independent random samples from those distributions.
- Evaluate the model for each sample to produce an output.
- Aggregate outputs to form an estimate, such as a mean, proportion, or quantile.
Why randomness helps when direct calculation is hard
Some problems are tractable analytically, but many are not. High-dimensional integrals, complex dependencies, or nonlinear transformations can make exact solutions impractical. Random sampling sidesteps these obstacles by turning a difficult global calculation into many simple local evaluations. The law of large numbers ensures that sample averages converge to the expected value, and the central limit theorem explains why the error typically shrinks at a rate proportional to one over the square root of the number of samples.
A simple illustration: estimating an area
A classic teaching example is estimating the area of a shape that is hard to integrate. Suppose you want the area of an irregular region inside a known rectangle. If you scatter points uniformly at random inside the rectangle and record the fraction that land inside the target region, that fraction multiplied by the rectangle’s area is an unbiased estimate of the region’s area. With enough points, the estimate stabilizes. This is not a practical way to compute every area, but it demonstrates the principle that random sampling can approximate complex quantities.
From sampling to decision-making
Monte Carlo methods are especially useful when the goal is to understand risk or variability rather than a single deterministic answer. By running thousands or millions of scenarios, you can build a distribution of possible outcomes. From that distribution, you can compute summaries such as means, medians, standard deviations, or tail probabilities. These summaries help analysts see not just the central tendency, but also how outcomes might vary and how likely different outcomes are.
Common building blocks
Several ingredients appear often in Monte Carlo work:
- Random number generators: Computers use algorithms that produce sequences of numbers that behave like independent draws from a distribution. These are pseudorandom numbers, but for most modeling purposes they are sufficiently unpredictable.
- Distributions: Uniform, normal, lognormal, exponential, and many other distributions model different kinds of randomness. Choosing the right distribution depends on the problem.
- Aggregation: Averages, proportions, quantiles, and variance estimates summarize simulation outputs.
- Convergence diagnostics: Tracking how an estimate changes as the sample size grows helps assess stability.
Accuracy and convergence
A key property of Monte Carlo estimation is that accuracy improves with more samples, but with diminishing returns. Because the standard error typically decreases with the square root of the number of samples, reducing error by a factor of ten requires about a hundred times more samples. This trade-off makes Monte Carlo methods robust but sometimes computationally expensive. It also explains why practitioners often balance accuracy targets against available time and computing resources.
Variance reduction: getting more from each sample
To improve efficiency, analysts use variance reduction techniques that make each sample more informative:
- Antithetic variates: Pairing each random draw with a complementary draw can reduce variability in the estimate.
- Control variates: If you know the expected value of a related quantity, you can adjust your estimator to reduce noise.
- Importance sampling: Sampling more heavily from regions that contribute most to the result can reduce variance, provided the adjustments are done correctly.
- Stratified sampling: Dividing the input space into strata and sampling within each can improve precision for certain problems.
These strategies do not change the underlying idea; they simply make the simulation more efficient.
Applications across fields
Monte Carlo methods appear in many areas where uncertainty and complexity meet:
- Physics and engineering: Modeling particle transport, heat flow, or complex systems with many interacting parts.
- Finance and economics: Evaluating models with stochastic dynamics and assessing the distribution of outcomes.
- Computer science and machine learning: Approximating intractable integrals, performing probabilistic inference, and training models with stochastic algorithms.
- Operations and logistics: Testing how variability in demand, lead times, or capacity affects performance.
In each case, the simulation lets analysts explore scenarios that are difficult to analyze in closed form.
Practical considerations
While Monte Carlo methods are flexible, good practice matters:
- Model quality: A simulation is only as meaningful as the model and assumptions behind it.
- Randomness management: Using fixed seeds and recording settings helps with reproducibility.
- Sample size: Choose a size that balances accuracy and computation. Monitor how estimates change as you add samples.
- Bias vs. variance: Ensure the estimator is appropriate for the question, and consider variance reduction when needed.
Key takeaways
Monte Carlo simulation is a practical way to tackle problems where direct calculation is difficult or impossible. By generating many random scenarios and aggregating the results, computers can estimate quantities, map out distributions, and quantify uncertainty. The approach is grounded in core probability ideas, scales with computing power, and benefits from a rich set of techniques to improve efficiency. For students and practitioners alike, understanding these basics provides a strong foundation for using simulation as a careful, transparent tool for analysis.