Home / Real-World Applications
Using Expected Value to Make Rational Decisions Under Uncertainty
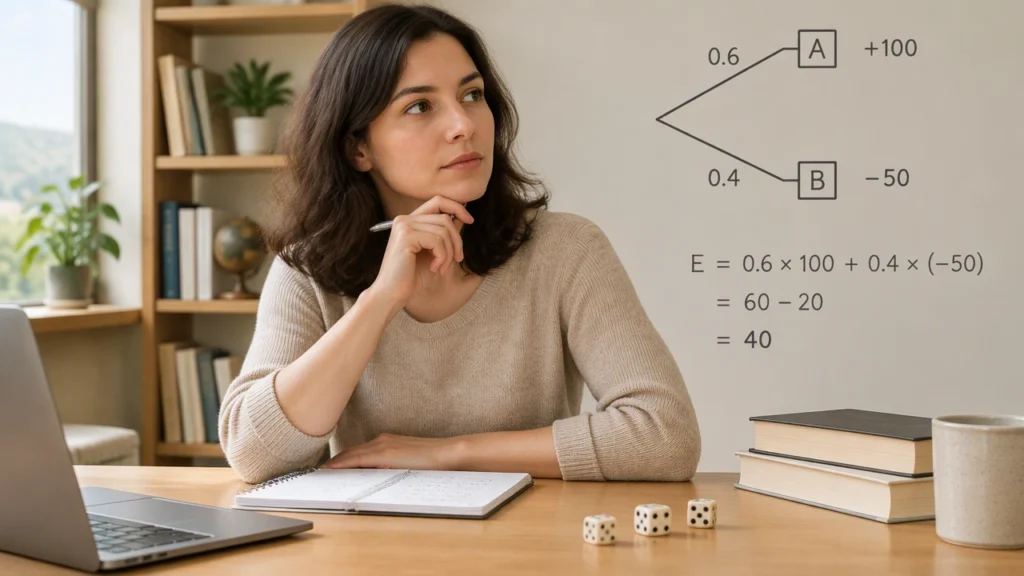
Probability gives us a language for uncertainty, and expected value turns that language into a practical decision tool. It does not predict what will happen in a single situation. Instead, it summarizes the long-run average outcome of a random process, helping you compare options on a common scale. Understanding how to calculate and interpret expected value is useful in personal finance, scheduling, maintenance, health, business, and everyday planning.
What expected value means
Expected value is the probability-weighted average of all possible outcomes. Each outcome is multiplied by its probability, and the results are added together. The result may be a number that could never occur in one trial, such as $18.40 when the possible values are $0 and $46. That is not a flaw. It represents the average you would approach over many repetitions.
A simple example is a repair that costs $120 with a 25% chance of occurring during the next year and nothing otherwise. The expected repair cost is:
0.25 × $120 + 0.75 × $0 = $30
The $30 is not a forecast that the repair will cost exactly $30. It is a useful summary for comparing alternatives, setting aside money, or deciding how much preventive maintenance might be worth.
How to calculate expected value
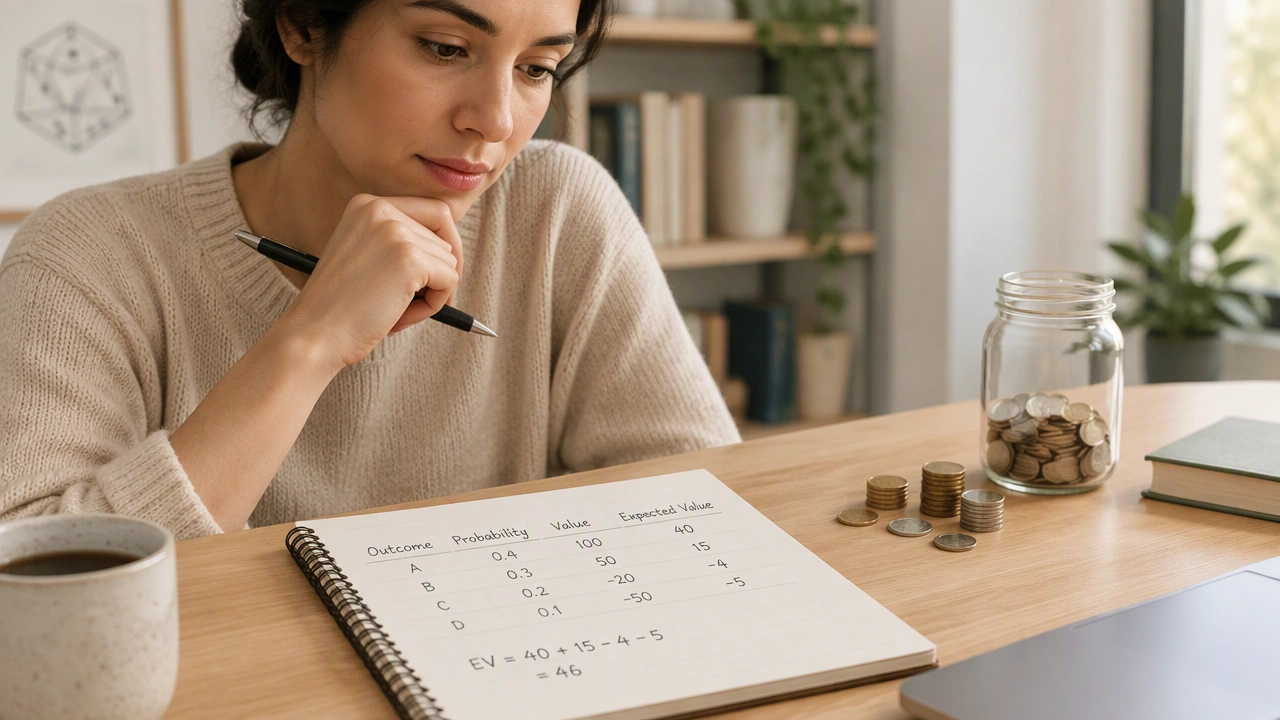
Start by listing every possible outcome. Assign each outcome a probability, making sure the probabilities add up to 1. Multiply each outcome by its probability, then sum the products.
Worked example: choosing between two routines
Suppose two routes to an appointment have different travel times because of traffic. Route A takes 30 minutes with probability 0.6 and 50 minutes with probability 0.4. Route B takes 40 minutes with probability 0.7 and 45 minutes with probability 0.3.
Route A: 0.6 × 30 + 0.4 × 50 = 18 + 20 = 38 minutes
Route B: 0.7 × 40 + 0.3 × 45 = 28 + 13.5 = 41.5 minutes
Route A has the lower expected travel time. That does not guarantee it will be faster today. Route A can still produce the worst possible delay. The calculation simply says that, if you faced the same conditions repeatedly, Route A would average less time.
Interpreting the result carefully
Expected value is most informative when outcomes can be compared on the same scale, such as money, time, energy, or risk-adjusted units. It is less helpful when a single result could be catastrophic and cannot be repeated. A low-probability event with a severe consequence may deserve attention even if its expected value looks small.
Consider equipment that fails with a 2% chance each year. If a failure costs $10,000, the expected annual loss is $200. A maintenance contract costing $300 per year has a higher expected cost, so a purely expected-value calculation would favor self-insuring. But the decision may change if the $10,000 loss would be impossible to absorb, if downtime would be dangerous, or if the contract includes rapid service. Expected value should be combined with an assessment of variance, worst cases, and personal or organizational constraints.
Using expected value in personal decisions
- Warranties and repairs: Compare the expected repair cost with the warranty price. Include the probability of failure, the repair expense, and any inconvenience or downtime.
- Subscription choices: Estimate how often you will use a service and multiply the value of each use by its likelihood. A cheap subscription used rarely may have a lower expected value than a higher-priced option used consistently.
- Time allocation: Treat time as a resource. If a task has a 70% chance of taking 20 minutes and a 30% chance of taking 60 minutes, its expected duration is 32 minutes. That estimate can improve scheduling.
- Preventive actions: Compare the expected cost of a preventable problem with the cost of prevention. Include both direct expenses and secondary effects such as lost productivity.
Expected value in business and public policy
Businesses use expected value to evaluate projects with uncertain returns. A product launch might generate $200,000 in profit with a 40% chance, break even with a 35% chance, and lose $100,000 with a 25% chance. The expected value is:
0.40 × $200,000 + 0.35 × $0 + 0.25 × (−$100,000) = $55,000
The positive result supports further analysis, but it does not settle the decision. Managers still need to consider funding limits, strategic fit, customer impact, and the possibility of a large loss.
In public policy, expected value helps compare interventions. A safety program may cost $2 million and prevent injuries with a certain probability. Decision-makers can estimate expected injuries avoided, expected lives saved, and expected costs per unit of benefit. Transparent assumptions allow different teams to challenge the inputs rather than argue only about conclusions.
Common mistakes to avoid
One mistake is confusing expected value with a guaranteed result. Another is using inaccurate probabilities. If the chance of failure is actually 10% rather than 2%, the expected cost changes substantially. Historical records, expert estimates, and sensitivity analysis can help test assumptions.
Another mistake is ignoring dependencies. If several uncertain events occur together, adding their separate expected values may be misleading. A flood and a power outage, for example, may be correlated, increasing the chance of a combined loss.
Finally, do not overlook nonfinancial outcomes. Reputation, safety, convenience, fairness, and emotional stress may not appear in a simple calculation. They can be included as explicit factors or discussed alongside the numerical result.
A practical decision habit
When facing an uncertain choice, write down the possible outcomes, estimate their probabilities, and calculate the expected value for each option. Then ask three follow-up questions: How variable are the outcomes? How bad is the worst case? Which assumptions matter most? This process will not remove uncertainty, but it will make your reasoning clearer and more consistent.
Expected value is a disciplined way to compare alternatives without pretending that the future is known. Used with careful assumptions and sound judgment, it supports rational decisions across many contexts, from routine scheduling to long-term planning.