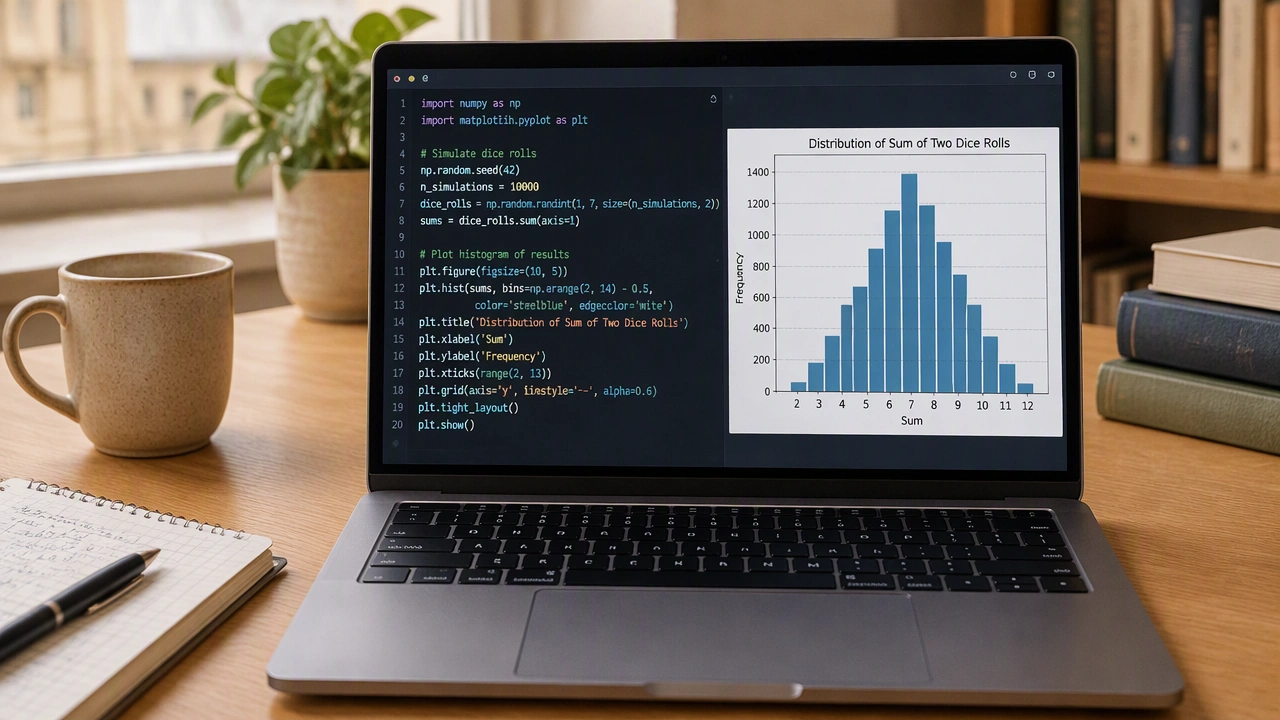
Monte Carlo simulation is a technique that uses repeated random sampling to approximate mathematical results that might be difficult to compute analytically. Named after the famous casino in Monaco, the method was developed by Stanislaw Ulam and John von Neumann during the Manhattan Project. Today, Python makes these simulations accessible to anyone with basic programming skills. Using libraries like NumPy and Matplotlib, you can simulate thousands of coin flips, dice rolls, or card draws to verify theoretical probabilities. In this thread, we share beginner-friendly Python code examples and walk through how simulations converge to expected values as the number of trials increases — a beautiful demonstration of the Law of Large Numbers. Post your own simulation projects, ask questions about the code, and discuss when simulation is more practical than exact calculation.